Summary
Discovering how to pay for memory care involves exploring multiple funding sources beyond personal savings to create a sustainable financial plan for your loved one living with dementia.
- Review long-term care insurance policies carefully, including daily benefit amounts, elimination periods, and coverage limits, then contact your insurance provider early to understand the claims process
- Eligible veterans and surviving spouses may qualify for VA pension benefits like Aid and Attendance; gather military service records and consult with the U.S. Department of Veterans Affairs or an accredited professional
- Understand that Medicaid coverage for memory care in Pennsylvania involves complex eligibility rules; consult a qualified attorney before making major financial decisions or asset transfers
- Explore life insurance policy options, including accelerated death benefits, borrowing against cash value, life settlements, or surrendering the policy—each with different tax implications
- Consider home equity strategies like lines of credit or reverse mortgages as alternatives to immediate home sale, while accounting for ongoing property expenses
Finding quality memory care for a loved one living with dementia can bring financial questions alongside emotional ones. Families wondering how to pay for memory care may be relieved to learn that several funding sources can help manage expenses without relying entirely on savings.
The right approach depends on your loved one’s finances, benefits, insurance coverage, and long-term plans. Understanding your memory care payment options can help your family build a more sustainable strategy while focusing on finding appropriate support for your loved one.
1. Review Long-Term Care Insurance Coverage
If your loved one has long-term care insurance, start by reviewing the policy closely. Depending on its terms, a policy may provide benefits that can be used toward memory care expenses.
When evaluating long term care insurance memory care coverage, pay attention to:
- The daily or monthly benefit amount
- The elimination period before benefits begin
- The total benefit pool and length of coverage
- Requirements for qualifying for benefits
Contact the insurance company early so you understand the claims process and documentation requirements. Knowing what the policy covers can also give you a clearer picture of how much additional funding your family may need.
2. Explore Veterans Benefits for Memory Care
Eligible veterans and surviving spouses may be able to use certain VA pension benefits, including Aid and Attendance, to help with long-term support expenses. Eligibility and benefit amounts depend on individual circumstances, including service history, financial qualifications, and support needs.
Families researching veterans benefits for memory care should gather military service records and relevant financial and medical documentation before beginning the application process.
Because eligibility rules can be complex, consider speaking directly with the U.S. Department of Veterans Affairs or an accredited veterans benefits professional. Starting early can be helpful because the application and review process may take time.
3. Understand Medicaid for Memory Care in Pennsylvania
Families researching Medicaid for memory care in Pennsylvania should understand that coverage is more complicated than simply applying Medicaid benefits toward a community’s monthly memory care fee. Eligibility and covered services depend on the individual and the specific program involved.
Before making financial decisions, families may want to:
- Review current Pennsylvania Medicaid eligibility requirements
- Ask the community which payment sources it accepts
- Consult a qualified elder law attorney about asset and eligibility rules
Professional guidance can be particularly valuable before transferring or spending significant assets. Medicaid rules include financial eligibility requirements and restrictions that can affect long-term planning, so families should avoid making major financial changes based solely on general advice.
4. Consider the Value in a Life Insurance Policy
A life insurance policy may provide another potential source of funds. Depending on the type of policy and its terms, families may have several ways to access its value.
Possibilities can include:
- Using an accelerated death benefit when policy requirements are met
- Borrowing against available cash value
- Exploring a life settlement
- Surrendering an eligible policy for its cash value
These choices can affect taxes, policy benefits, and the amount eventually available to beneficiaries. A financial or insurance professional can explain the implications before your family makes a decision.
5. Explore Home Equity Without Immediately Selling
For families interested in paying for memory care without selling house assets, home equity may offer options beyond an immediate sale. Depending on the homeowner’s circumstances, possibilities could include a home equity line of credit, a reverse mortgage, or renting the property to generate income.
Each strategy has different requirements, costs, and long-term consequences. For example, keeping a property also means accounting for taxes, insurance, maintenance, and other ongoing expenses. Families should consider whether retaining the house makes financial sense as part of the broader plan rather than viewing home equity as an isolated funding source.
Build a Plan Around Your Family’s Needs
Paying for memory care often involves combining resources rather than relying on a single solution. Insurance, veterans benefits, personal assets, home equity, and applicable public programs can all be worth investigating.
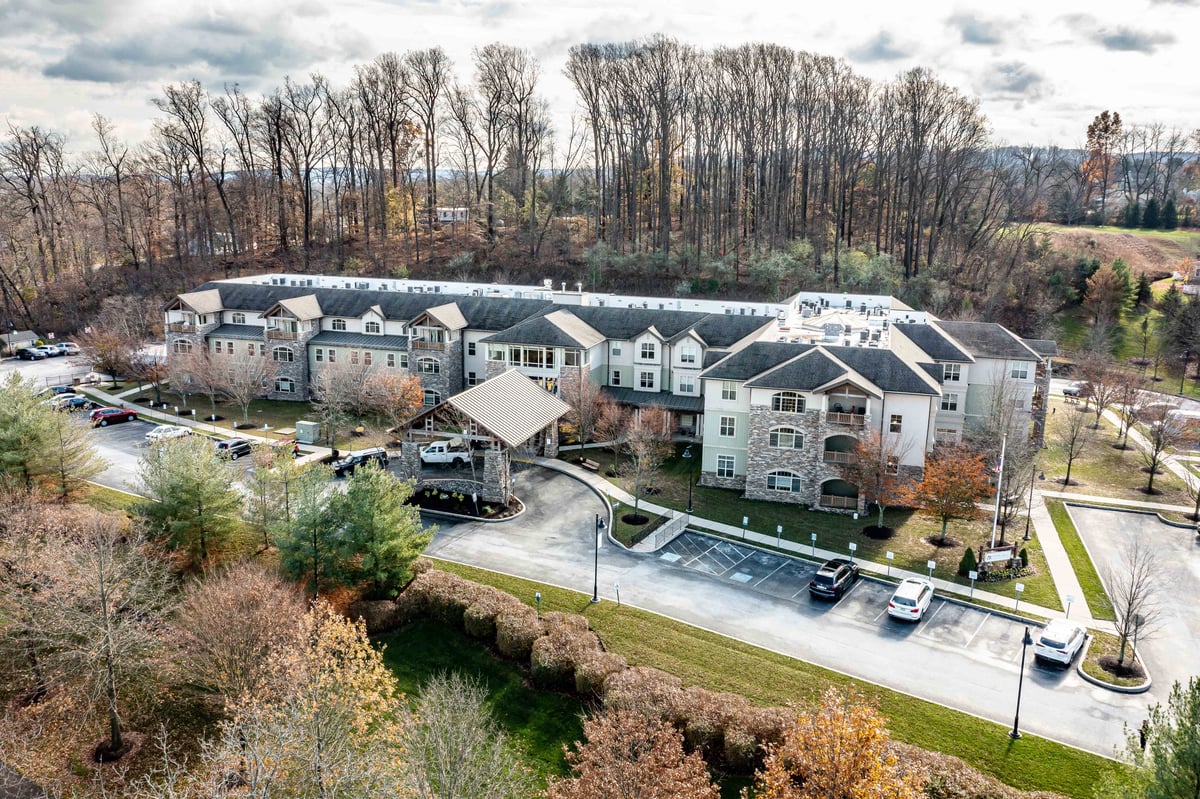
For families in Phoenixville, Spring Mill offers SHINE® Memory Care, a personalized program nationally recognized by the Alzheimer’s Association®. Residents can also enjoy chef-prepared Sensations Dining, engaging Celebrations programs, housekeeping, scheduled transportation, and thoughtfully designed community spaces. Understanding both the services included and available financial resources can help families create a clearer plan for the next chapter.
Schedule a tour of Spring Mill to explore SHINE® Memory Care, discuss current pricing and services, and learn more about creating a plan that works for your family.